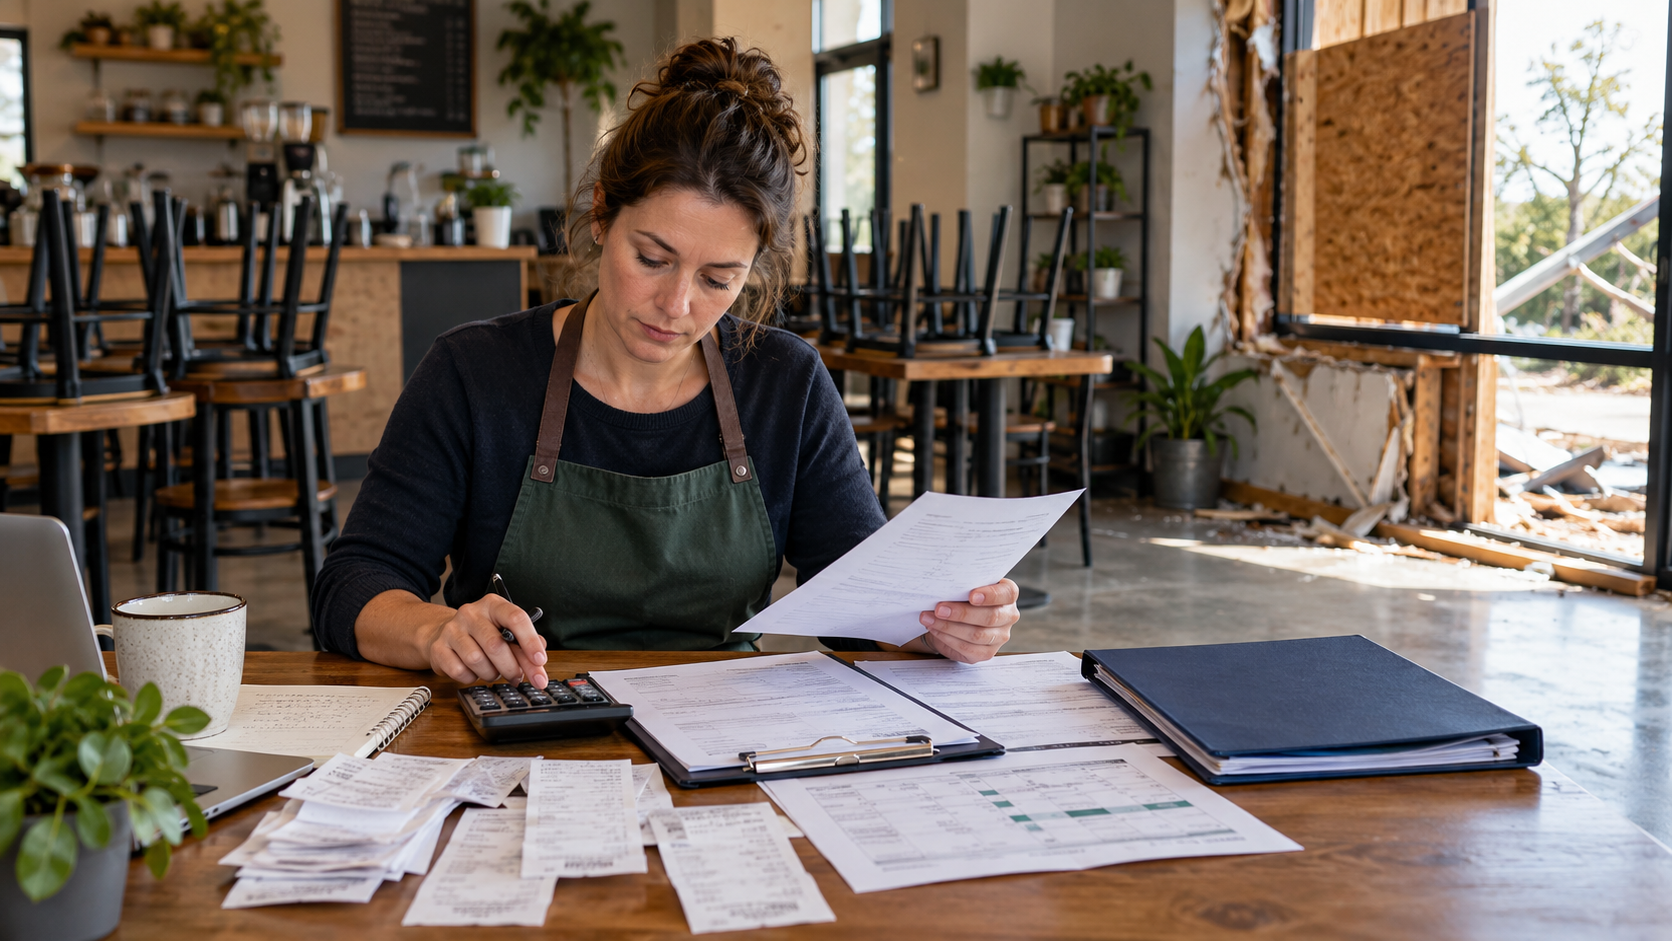
When a fire, wind and hail storm, or other covered loss damages your business property, the repair bill is only part of the cost. You may also lose income while you are closed or running at reduced capacity, and spend extra money to keep serving customers.
That second layer is usually handled under business income and extra expense coverage (often called business interruption). It is typically part of a commercial property policy or business owner's policy (BOP), but it has rules many small-business owners do not see until they need them. This post explains waiting periods, the period of restoration, and the documents that usually drive the claim. Every policy is different, so your declarations and coverage form control.
What Business Income Coverage Is For
Depending on your policy, business interruption coverage typically includes:
- Business income: the net income you would have earned, plus continuing normal operating expenses, during the period of restoration
- Extra expense: reasonable costs to avoid or shorten a shutdown — temporary space, rented equipment, overtime, expedited shipping
- Extended business income: a limited period after you reopen while revenue recovers
- Ordinary payroll: if included, for a set number of days
- Civil authority: lost income when a government order blocks access because of nearby covered damage (when that coverage applies)
Coverage is generally triggered by direct physical loss or damage from a covered peril. If the property damage is not covered, the related income loss usually is not either.
We do not handle NFIP flood claims. If your commercial policy includes flood by endorsement, we can review a related business interruption claim like any other covered loss.
Waiting Period (Baseline Only)
Many policies do not pay for the first stretch of lost income. A common baseline in industry form language is around 72 hours (sometimes expressed as three consecutive days) after the direct physical loss. That is only a baseline. Your policy may set a longer waiting period, a different trigger, or apply the waiting period only to business income and not to extra expense. Check your declarations and the business income form; do not assume 72 hours.
Period of Restoration, in Plain English
The period of restoration is the window the policy uses to measure how long income loss is payable. In plain terms, it is usually the time it should reasonably take to repair or replace the damaged property — starting after any waiting period — not necessarily until you actually reopen or until every customer comes back.
That distinction matters. If repairs are delayed for reasons the insurer argues were avoidable, or if the carrier's repair schedule is shorter than your contractor's, you may see pushback on how long income loss continues. Extended business income, when included, can add a limited recovery period after operations resume.
For fire losses, documenting the property damage early supports both the building claim and the income claim. See our guide to the first 48 hours after a house fire for the property side of that work.
Documents You Will Likely Need
Business income claims live or die on financial records. Talk with your accountant early and gather:
- Profit and loss statements for prior years and the months before the loss
- Business tax returns for recent years
- Monthly or weekly sales records leading up to the loss
- Payroll records and a list of continuing expenses (rent, loan payments, utilities, key contracts)
- Receipts and invoices for every extra expense
- Contractor schedules showing how long repairs should take
- Records of closures, reduced hours, canceled orders, and sales after reopening
Keep a running log of decisions you made to stay open or reopen sooner. Insurers often ask what you did to mitigate the income loss.
What to Do First
- Report both the property damage and the business income loss to your insurer.
- Take reasonable steps to keep operating or reopen sooner, and document what you did.
- Track every extra expense separately, with receipts.
- Keep records of closures, reduced hours, and canceled orders.
- Ask the insurer to confirm proof-of-loss and suit deadlines in writing.
Our property insurance claim process guide covers the typical claim timeline alongside the income piece.
Insurer Pushback You May See
Common friction points include:
- A shorter period of restoration than the actual repair schedule
- Disputes over projected sales and seasonality
- Arguments that lost income came from the economy or other factors, not the loss
- Denial of extra expenses as unnecessary
- A coinsurance penalty when the business income limit was underinsured
Stay organized, put numbers in writing, and keep copies of every submission.
Texas, Louisiana, and Mississippi Notes
Each state sets rules for how quickly insurers must acknowledge, investigate, and pay claims. Coastal businesses should confirm whether wind damage sits on the commercial policy or a separate wind policy, because business income coverage generally follows the property coverage that applies to the loss.
Licensing note: All Perils Consulting is licensed for public adjusting in Texas and Louisiana. Mississippi work is handled under an individual license at this time.
These notes are general. Your policy and current state law control.
When to Call a Public Adjuster
Consider getting help when:
- The property claim and the income claim are being handled on different tracks and the numbers do not line up
- The carrier's period of restoration looks shorter than a realistic repair schedule
- Extra expenses are being denied or projected sales are disputed
- You need help coordinating your accountant's work with the insurance demand
A public adjuster works for you, not the insurance company. We coordinate the property damage claim with the income claim, work with your accountant on the numbers, document the period of restoration and extra expenses, and negotiate with the insurer. Learn more about when a claim consultant can help and our public adjusting services.
Dealing with a business income claim after a fire or storm? Call 877-5APC-247 (877-527-2247) or contact us. We can review your commercial policy and the insurer's position with you.
Frequently Asked Questions
What is business interruption insurance?
It is coverage, usually called business income and extra expense, that pays lost net income and continuing expenses when a covered property loss forces a business to close or slow down. It is typically part of a commercial property policy or business owner's policy.
Is there a waiting period before business income coverage starts?
Many policies have a waiting period, often around 72 hours, before lost income is covered. That is a common baseline only. Your policy may set a longer waiting period, so check your declarations and coverage form.
How long does business interruption coverage last?
Typically for the period of restoration: the time it should reasonably take to repair or replace the damaged property, sometimes followed by a limited extended period while revenue recovers. It is not always the same as the day you actually reopen.
What records do I need for a business income claim?
Usually prior years' profit and loss statements and tax returns, recent monthly sales, payroll records, a list of continuing expenses, and receipts for extra expenses. Contractor schedules and post-reopening sales help too.
Does business interruption cover lost income if only part of the building was damaged?
It can, if the covered physical damage caused a slowdown or partial shutdown and your form covers that loss of income. The analysis is fact-specific: what was damaged, what operations were affected, and what your policy language says about partial suspensions.
All Perils Consulting Inc. is a licensed public adjusting firm. We are public adjusters, not attorneys, and this article is general information, not legal advice. Every claim and policy is different.
Free claim review
Questions about your claim?
Tell us what happened. A licensed public adjuster will look over your claim and policy and explain your options.
Get a free claim review